
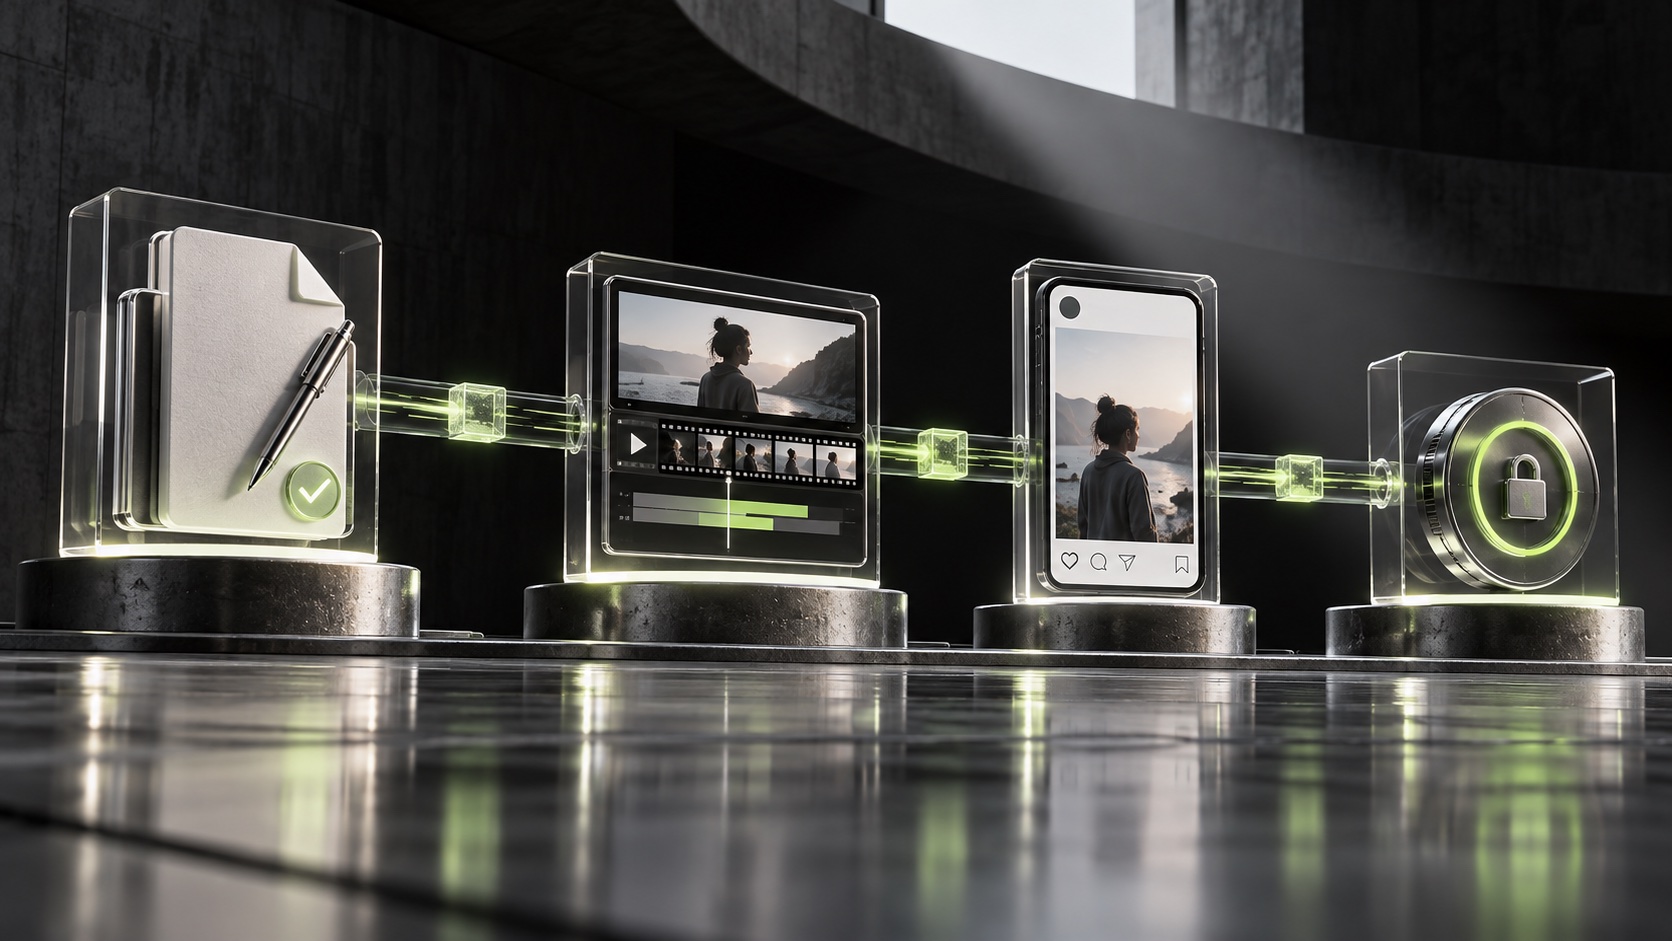
A creator milestone should release payment for a clearly defined unit of accepted work. Name the deliverable, evidence, approver, review window, correction path, and release condition before funding or production begins.
Splitting one collaboration into stages can balance creator cash flow with brand approval risk, but only when every stage is observable. Labels such as 'draft done' or 'campaign complete' are too vague to operate.
There is no universal split. Production costs, cancellation exposure, posting obligations, and the party controlling final approval should determine the schedule.
Give every milestone six operating fields
| Field | Question | Example |
|---|---|---|
| Deliverable | What unit is due? | First complete vertical-video draft |
| Evidence | What proves submission? | Review link with timestamp |
| Criteria | What must be true? | Approved claims and required product shot included |
| Reviewer | Who decides? | Named brand producer |
| Window | How long may review take? | Two business days |
| Release | What event triggers payment? | Written acceptance recorded |
Test the schedule against real work and risk
For an illustrative $5,000 collaboration, one schedule might assign 20% at signing, 35% after an accepted draft, 30% after verified publishing, and 15% after final files and agreed reporting. The corresponding amounts are $1,000, $1,750, $1,500, and $750.
This split is not a recommendation or product rule. It demonstrates how percentages must total 100% and how each payment can map to an observable stage.
Define approval, correction, and scope change separately
A correction brings submitted work into the agreed brief. A new direction changes the brief after production. Keep those paths separate so an included revision does not become an unlimited reshoot obligation.
State what happens when feedback is late, conflicting, or incomplete. Do not describe silence as approval unless the agreement and applicable rules clearly support that mechanism.
Keep the evidence with the payment record
The IRS describes invoices, receipts, account statements, and credit card slips as examples of supporting business records and notes that proof of payment alone may not establish the underlying business purpose.[1]
Operationally, retain the scope, submission, approval, invoice, payment reference, currency, and fees together. Ask qualified advisers which records and retention periods apply to your organization and market.